What Is MICA? Key Points of EU Crypto Regulation
MICA (correctly written MiCA, Markets in Crypto-Assets Regulation) is the EU's first comprehensive regulation for crypto-assets. It brings token issuance, trading platforms, custody, stablecoins and market manipulation all under a single unified licensing and disclosure framework.
On July 1, 2026, MiCA's transition period officially ended. Crypto-asset service providers without authorisation can no longer offer services in the EU. This is a watershed for exchanges, stablecoin issuers and ordinary investors alike. This article breaks down MiCA's scope, licensing requirements, stablecoin rules and how implementation is actually playing out in 2026.
Key Takeaways
- MiCA is the EU's crypto-asset regulation (EU 2023/1114), which entered into force in June 2023 and has applied in phases since 2024.
- It divides tokens into ART, EMT and other crypto-assets, and applies a CASP licensing regime to ten categories of services including exchanges, custody and advisory.
- Stablecoins (EMT/ART) must hold 1:1 reserves, be redeemable at par and must not pay interest; "significant" tokens face additional, stricter requirements.
- The transition period ended on July 1, 2026. Unlicensed CASPs may no longer serve EU clients; compliance costs have risen, and the market has seen exchange delistings and consolidation.
What Is MICA (MiCA)?
MiCA's full name is Markets in Crypto-Assets Regulation, regulation number (EU) 2023/1114. Its goal is to create a single consistent set of crypto-asset rules for the EU's 27 member states, replacing fragmented national regimes. For businesses, the biggest draw is the "passporting" regime: once licensed in one member state, a firm can provide services in the others.
MiCA entered into force on June 29, 2023, but applies in phases: the rules for asset-referenced tokens (ART) and e-money tokens (EMT) have applied since June 30, 2024; the rules for crypto-asset service providers (CASP) have applied since December 30, 2024. Member states could opt for a transition period of up to 18 months, which ultimately ended on July 1, 2026.
Note that MiCA is neither a "crypto legalisation" act nor a "crypto ban" act. It is a set of market rules: what can be issued, who can sell it, what must be disclosed, how reserves are held and how client assets are segregated. For investors, it brings more protection but also fewer product choices.
What Does MiCA Cover? Three Token Categories and Ten Services
MiCA's scope covers crypto-assets "not covered by other EU financial regulation". In other words, financial instruments already caught by rules such as MiFID II do not become MiCA assets simply because they are tokenised; central bank digital currencies, deposits, insurance and pension products are also out of scope. NFTs are in principle excluded, but may still be captured if issued or fractionalised in a fungible manner.
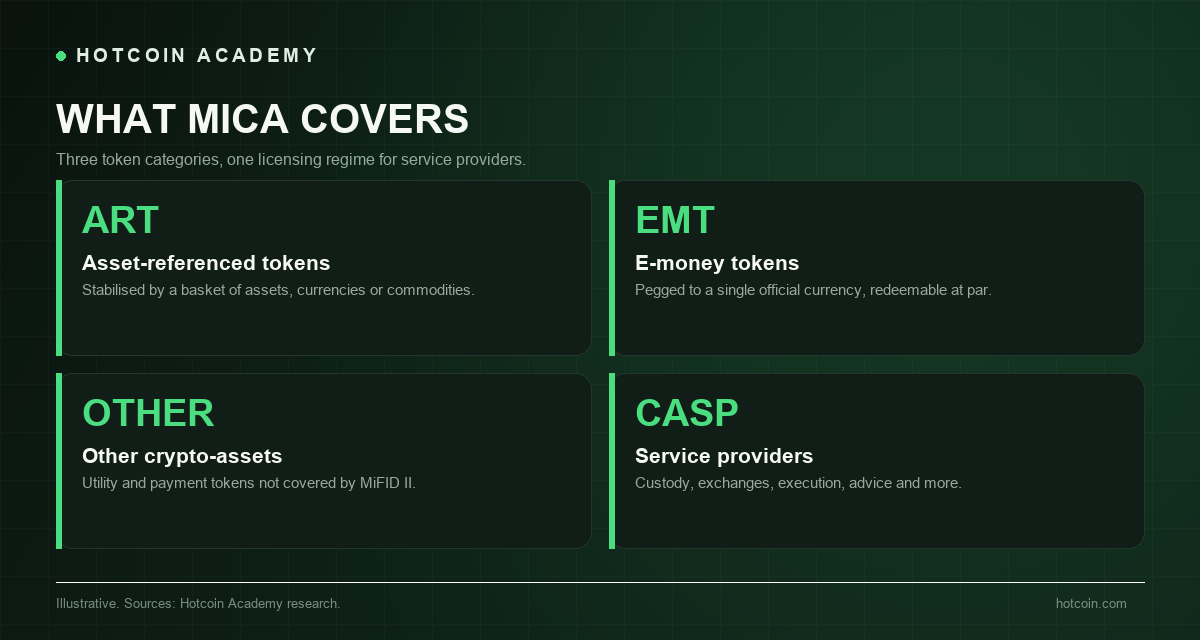
Figure: MiCA's three token categories and CASP service providers.
Category | Definition | Main requirements |
ART (asset-referenced token) | Stabilised by a basket of assets, currencies or commodities | White paper, reserves, governance, redemption, capital requirements |
EMT (e-money token) | Pegged to a single official currency, redeemable at par | 1:1 reserves, no interest, redemption rights, reserve segregation |
Other crypto-assets | Neither ART/EMT nor MiFID II instruments | White paper, marketing rules, consumer protection |
CASP (service provider) | Provides trading, custody, exchange, advisory and other services | Authorisation, capital, governance, client asset segregation |
Classification and requirements are subject to MiCA provisions and national regulator guidance.
The ten CASP services are: custody and administration of client crypto-assets, operation of a trading platform, exchange of fiat for crypto-assets, exchange of crypto-assets for other crypto-assets, execution of orders, placement of orders on behalf of clients, reception and transmission of orders, provision of investment advice, portfolio management, and underwriting and distribution. Offering any one of these in the EU may require a licence.
CASP Licences: Capital, Governance and Client Protection
MiCA's core requirements for CASPs come down to three things: capital, governance and client asset segregation. Capital requirements are divided into three tiers by service type, from around EUR 50,000 at the low end to around EUR 150,000 at the high end; larger firms or those offering multiple services must also meet a fixed-expenses ratio.
- Authorisation and passporting: Apply to the home-state regulator; once granted, services can be offered in other member states.
- Governance and fitness: Management and shareholders must meet fit and proper requirements and have clear conflict-of-interest policies.
- Client asset segregation: Client assets must be held separately from the firm's own assets, with succession planning and safe-custody arrangements.
- Disclosure and complaints: Fees, risks and execution quality must be clearly disclosed, and a complaints-handling mechanism must be established.
- Market manipulation and insider trading: MiCA introduces MAR-like market abuse rules prohibiting manipulation and insider trading.
These requirements are not difficult for large exchanges, but they are a heavy fixed cost for smaller players. In the first half of 2026, around 80% of European crypto firms had not yet obtained a MiCA licence, and some chose to exit the market, partner with licensed firms, or be acquired.
Stablecoin Rules: The Difference Between EMT and ART
MiCA's stablecoin regulation is the most closely watched part of the whole framework. EMTs are pegged to a single fiat currency (usually the euro or US dollar); issuers must hold 1:1 reserves, redeem at par and must not pay interest to holders; reserves must be segregated from the issuer's own assets and are subject to regulator inspection. ARTs maintain stability through a basket of assets, and their rules are closer to asset management.
If a token is deemed "significant" — for example, if user numbers, market capitalisation or cross-border use reach a threshold — regulatory requirements are raised further, including stricter capital, liquidity and recovery plans. This is why some US dollar stablecoins face particularly high compliance costs in the EU: their scale is so large that it is hard not to treat them as significant tokens.
In practice, in 2026 several European exchanges have restricted or delisted non-compliant USDT trading pairs and steered users toward compliant EMTs. For users, this means "the stablecoin you know" may not be usable in compliance with EU rules; for issuers, it is a trade-off between compliance and market share.
The 2026 Timeline and Implementation Status
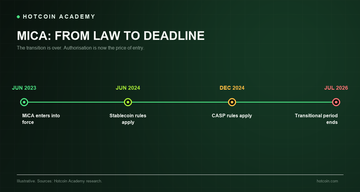
Figure: MiCA's timeline from legislation and phased application to the end of the transition period in 2026.
2026 is the year MiCA turns from "rules on paper" into "market reality". After the transition period ended on July 1, unlicensed CASPs may no longer serve EU clients; ESMA's interim register continues to update lists of compliant and non-compliant firms; national regulators have begun cracking down on unlicensed operations.
- Faster licensing: Ripple obtained a full CASP authorisation in July 2026, allowing it to serve 30 EEA countries; traditional banks such as CaixaBank have also obtained MiCA licences.
- Exchanges adjusting products: Platforms including Binance, Coinbase and Kraken have restricted or delisted non-compliant stablecoins in Europe and added compliant trading pairs.
- Market consolidation: Smaller players are exiting due to compliance costs, with licensed platforms and banks the main beneficiaries.
- Rules still evolving: ESMA and EBA continue to issue technical standards and guidance, and firms must keep adapting.
How MiCA Affects Exchanges and Investors
For exchanges, MiCA is a kind of "compliance Darwinism". Large platforms can afford the legal, risk-control and capital costs and can expand through passporting; smaller platforms may exit, pivot to becoming technology suppliers, or partner with licensed institutions. For investors, the short term brings fewer trading pairs, stricter KYC and clearer fee disclosure.
In the long run, MiCA's value lies in "comparability": white papers, reserves, fees and risk disclosures follow a uniform format, so investors comparing different products do not have to start from scratch each time. But regulation does not eliminate market risk; it only shifts risk from "information asymmetry" to "price volatility".
Aspect | Before MiCA | After MiCA |
Market access | Rules differ by country; some regions require no licence | Unified licensing and passporting |
Stablecoins | Inconsistent reserve and redemption rules | 1:1 reserves, redemption at par, no interest |
Client assets | Segregation requirements vary | Mandatory segregation and succession planning |
Disclosure | White paper quality varies | Uniform white papers and fee disclosure |
Product choice | More non-compliant tokens | Compliant tokens prioritised; some delisted |
This comparison is a conceptual summary; actual application depends on national regulators and product structures.
MiCA, Hong Kong and the US: Three Regulatory Paths
In 2026, major markets have all established crypto regulatory frameworks, but along different paths. The EU takes a "comprehensive unified licensing" approach, Hong Kong a "dual-track licensing for stablecoins and trading platforms", and the US a division of labour between a "federal payment stablecoin law + securities law". All three have similar stablecoin requirements (1:1 reserves, redemption, disclosure), but differ greatly on token issuance and trading platform rules.
Market | Core legislation | Features | Challenges for firms |
EU | MiCA | Unified licensing, passporting, comprehensive disclosure | High compliance costs, complex detailed rules |
Hong Kong | Stablecoins Ordinance, VASP regime | Separate licensing for stablecoins and trading platforms | High licensing thresholds, smaller market |
US | GENIUS Act, securities law | Federal stablecoin framework, case-by-case SEC oversight | Rules still forming, state and federal regimes in parallel |
Regulations keep updating across jurisdictions; cross-border businesses need to assess multiple markets at once.
Common Misconceptions
- "MiCA bans cryptocurrency": MiCA is a set of market rules, not a ban; it regulates issuance and services, not holding.
- "MiCA covers all NFTs": most NFTs are excluded, but may be captured after fractionalisation or fungibility.
- "Getting a MiCA licence means you're safe": a licence means compliance, not that a platform won't fail or be hacked.
- "MiCA only affects EU companies": any firm serving EU clients may need authorisation, even if based outside the EU.
FAQ
What is the difference between MICA and MiCA? They refer to the same regulation. The correct abbreviation is MiCA (Markets in Crypto-Assets); "MICA" is a common spelling, and both appear in searches.
When did MiCA take effect? MiCA entered into force in June 2023; stablecoin rules have applied since June 30, 2024, and CASP rules since December 30, 2024. The transition period lasted up to 18 months and ended on July 1, 2026.
Does MiCA affect ordinary investors? Yes. You may see stricter KYC, clearer fee disclosure, fewer non-compliant trading pairs and some stablecoins delisted. Client asset protection if a compliant platform fails is also clearer than before.
What does MiCA require of stablecoins? EMTs must hold 1:1 reserves, redeem at par and pay no interest, with reserves segregated from own assets; ARTs have additional basket-asset and governance requirements. Tokens deemed "significant" face stricter capital and liquidity requirements.
Does Hong Kong have similar rules? Yes. Hong Kong's Stablecoins Ordinance took effect on August 1, 2025, with the HKMA licensing and supervising fiat-referenced stablecoins; trading platforms are regulated under the SFC's VASP regime. The two regimes are similar, but scope and licensing processes differ.
Conclusion
MiCA's significance is not just that "the EU has started regulating crypto", but that it pulls the crypto market out of an exceptional state and into general financial regulation. It raises the bar and also raises predictability; for large compliant firms it is an opportunity, for smaller ones a pressure.
For investors, MiCA won't save you from losses, but it makes it easier to compare platforms and products. Understanding MiCA's classification, licensing and stablecoin rules is basic groundwork for judging whether an exchange can operate in Europe for the long term. To track regulatory changes and market impact, read Hotcoin Academy's regulatory coverage.
Risk warning: This article is for educational and informational purposes only and does not constitute legal or investment advice. Regulatory rules and implementation details may change; for actual application, consult a professional legal adviser or refer to regulator announcements.
Đề xuất đọc
Xem thêm